
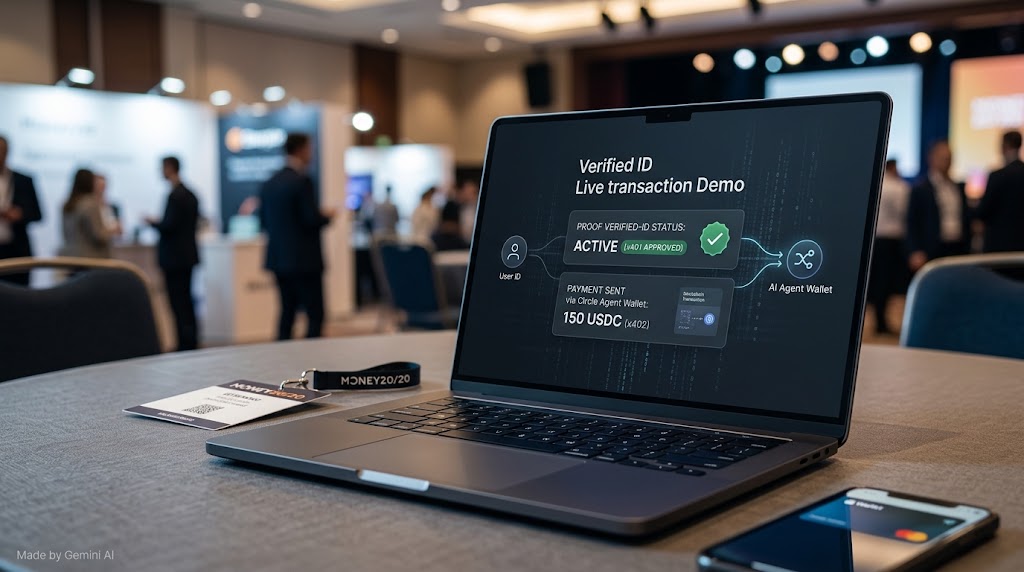

Circle Internet Group (NYSE: CRCL) and identity infrastructure firm Proof have unveiled a collaboration at Money20/20 in Las Vegas last week, demonstrating how verified legal identity and stablecoin payments can be combined in a single agent-initiated transaction. The demo addresses one of the more pressing structural problems in agentic commerce: merchants currently have no reliable way to know who authorised a purchase made by an AI agent, leaving them to choose between blocking agents outright or accepting the associated fraud and chargeback risk.
How the protocols fit together
The integration draws on two open HTTP-layer standards. Proof’s x401 protocol, published in June 2026 and moved into production last week, uses the HTTP 401 “Unauthorised” response to let a merchant specify what identity proof it requires and which credential issuers it trusts. Circle’s x402 protocol uses the HTTP 402 “Payment Required” response to specify how the agent should pay. Used in sequence, x401 answers who the agent acts for, and x402 answers how it settles the transaction.
In the demo flow, a merchant responds to an inbound agent request with both an x401 identity requirement and an x402 USDC payment request. The agent’s Proof wallet presents a verified credential derived from identity proofing certified to NIST IAL2 standard, accompanied by a signed, purchase-specific approval. Only the relevant identity facts are disclosed; no full ID document is transmitted or stored by the merchant. The agent then pays from a Circle Agent Wallet in USDC over x402. The merchant retains signed, tamper-evident evidence of who authorised the transaction, which can be used in dispute resolution without requiring Proof to be called again in real time.
A secondary mechanism embedded in the protocol stack is commercially notable. Proof prices identity claims individually, and the same x402 channel can route a micropayment from the merchant to the identity issuer for each verification used. That removes the bilateral contract requirement that has historically limited the reuse of verified identity across ecosystems: a merchant can pay for a check on the spot, at the moment it needs it, without a prior sales relationship with the credential issuer.
Pat Kinsel, founder and chief executive of Proof, said: “Our demo with Circle shows one exchange can answer both questions: verified identity from Proof and payment in USDC. That gives businesses a reason to say yes to agents instead of blocking them.”
Market context and regulatory read-across
The timing is pointed. Several large institutions at Money20/20 are understood to be blocking AI agent traffic entirely, a posture that carries its own commercial cost as consumer adoption of AI assistants accelerates. The Proof and Circle approach is one of several competing frameworks attempting to resolve agentic identity, alongside emerging work in the W3C verifiable credentials ecosystem and proprietary agent-authentication layers from payment networks and cloud providers.
From a regulatory perspective, the NIST IAL2 credential anchor is significant. That standard is referenced in US federal identity frameworks and is gaining traction in Know Your Customer discussions as a benchmark for remote identity proofing. In the UK, the Digital Identity and Attributes Trust Framework published by the Department for Science, Innovation and Technology sets comparable requirements, suggesting that a credential meeting IAL2 could attract recognition in cross-border contexts. The European eIDAS 2.0 wallet framework similarly defines trust levels against which x401-type presentations could eventually be assessed. Whether regulators will accept protocol-layer identity assertions as satisfying KYC obligations under anti-money laundering rules remains an open question, and one that will shape how quickly financial institutions can adopt agent-native payment flows rather than routing them through existing customer-authenticated channels.
AI level 1 of 5: written by Darlyn Ho; AI helped with tone, structure or wording; edited and signed off by Mark Walker, Editorial Director. What the levels mean